Here's the short version.
- Uninsured/underinsured motorist (UM/UIM) coverage on your own policy may pay when the other driver cannot.
- Texas insurers must offer UM/UIM and PIP, and you only lose them if you rejected them in writing.
- For a hit-and-run, call police right away. Your insurer may also ask for proof of contact with the other car.
- A UM/UIM claim is against your own company, but it may still treat you like an opponent.
Not every driver on Texoma roads carries insurance, even though Texas law requires it. Some carry only the state minimum. And some drivers panic or are hiding something and simply keep going, whether on a dark county road near Tom Bean or in a busy parking lot off US-75. Here is how these claims usually work.
Start with your own policy
Pull up your declarations page, the summary page of your auto policy. Look for:
- Uninsured/Underinsured Motorist (UM/UIM) bodily injury: pays for your injuries when the driver at fault is uninsured, underinsured or unknown.
- UM property damage: covers your car, often with a deductible.
- Personal Injury Protection (PIP): pays toward medical bills and missed income whoever caused it, starting at $2,500.
- Collision: fixes your vehicle whoever was at fault, less your deductible.
Texas requires insurers to offer UM/UIM and PIP. If you never signed a written rejection, you may have the coverage even if you do not remember choosing it. Request any rejection form with your signature on it.
If the other driver carried nothing
State law sets a 30/60/25 liability minimum for every driver. When someone does not, your UM coverage may step into their shoes and pay what their insurer would have paid, up to your limits. You may also be able to pursue the driver personally, though people driving without coverage rarely have much to collect.
When they do not have enough
Minimum coverage of $30,000 per person can be used up quickly by an ER visit, a few weeks of therapy and lost pay. Once their insurer pays out its limit, your underinsured coverage may make up the gap, as far as your own limits go. Your insurer may want to be notified before you accept the other driver's policy limits, so check with them first.
Hit-and-run steps
- Do not chase the driver. Stay safe and call 911.
- Write down everything you remember: color, make, plate letters, damage, direction they went.
- Look for cameras. Stores, gas stations, homes with doorbell cameras and traffic cameras. Ask quickly, since footage is often recorded over.
- Get witness names.
- Report promptly to police and your insurer. Many UM policies require prompt reporting of a hit-and-run.
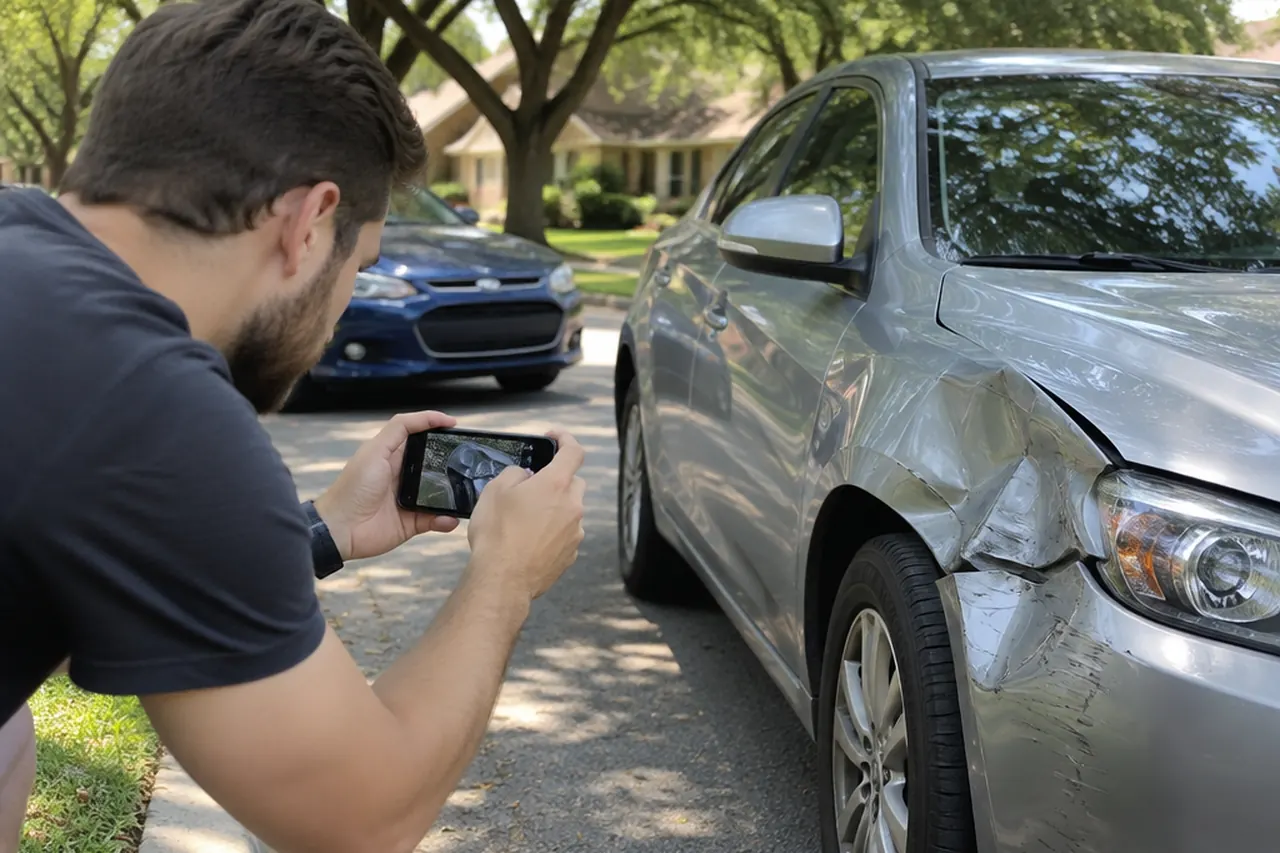
- Photograph paint transfer and damage on your car. Many policies require proof of actual physical contact with the other vehicle for an unknown-driver claim.
Fleeing an injury wreck is a crime in Texas. Should police track the driver down, a claim against them and any insurer may open up too.
Your own insurer may push back
It feels odd, but in a UM/UIM claim your insurer generally steps into the at-fault driver's shoes. Expect questions about how the wreck happened, how hurt you are and whether the care was needed. Treat it with the same care you would the other side's adjuster:
- Keep communication in writing when you can.
- Be careful with recorded statements.
- Send records and bills promptly, and keep copies.
If a claim under your own policy stalls, Texas prompt-payment rules and the Texas Department of Insurance's complaint process may help. See our insurance claims guide.
If you were walking, biking or riding
UM and PIP coverage can sometimes protect you even when you were not in your car. See our pages on pedestrian and bicycle accidents and motorcycle accidents.
When the driver is from Oklahoma
Oklahoma drivers are common around Sherman. If the driver is identified but uninsured, the same UM rules generally apply, and Texas law still generally controls a wreck here. Our article on Oklahoma driver crashes in Texas has more.
Parking lot hits and parked cars
Some hit-and-runs happen while you are not even in the car. You come out of a store on Texoma Parkway or an apartment lot near downtown and find a crushed fender and no note. In that case:
- Take photos right away, before moving the car.
- Look around for anyone who saw it, and check for a note on the windshield.
- Ask the business whether its cameras cover the lot, and how long they keep video.
- Report it to police and your insurer.
A Texas driver who strikes a parked, empty car must stop and track down the owner or leave a note with a name and contact details. When they do not, your collision or UM property damage coverage may help, subject to your deductible and policy terms.
Other policies in your household
Your own policy may not be the only one that helps. Depending on how the policies are written, UM/UIM on a policy belonging to a relative in your home may also protect you, especially if you have no car yourself. As a passenger in a friend's car, that car's policy may pay first, with yours adding on top. Insurance policies have their own rules about which coverage pays first and whether coverages can be combined. Ask each insurer for a written answer and keep copies, since these questions are easy to lose track of.
Deadlines still apply
Do not let an unknown driver or slow insurer run out the clock. The usual two-year deadline for injury claims may matter, and your policy may have its own notice and cooperation rules. Hurt and getting the runaround? Our free case review reaches an independent Texas attorney at no cost, or call (903) 357-5775.
Sources
Questions & answers
Will a UM claim raise my insurance rates?
It depends on your policy and insurer. Ask your agent. A UM claim is generally made because someone else caused the crash.
What if I never signed a rejection of UM coverage?
Every Texas insurer has to offer UM/UIM, and turning it down generally takes a signature. If you did not sign a rejection, you may have the coverage.
Do I need proof the hit-and-run car touched mine?
Many policies require proof of physical contact for an unknown-driver claim. Photos of paint transfer and damage, and witness statements, can help.
Related